Some borrowers are creditworthy but come with a layer of complexity that conventional lenders won’t touch — a few late payments, a recent credit event, or income that doesn’t fit standard documentation requirements. LendSure Mortgage Corp. (NMLS #1326437) offers Expanded Approval Non-QM loans designed for borrowers who are just outside agency guidelines but have the assets, income, and overall financial profile to support repayment.
If you have a borrower who keeps falling just short of conventional approval, submit your scenario and our team will review it within 24 hours.
Program Highlights
- Loan amounts up to $3,000,000
- LTV up to 85%
- Cash-out up to $1,000,000
- Flexible on bank NSFs and overdrafts
- Pre-qualification in as little as 24 hours
- Primary Residence or Second Homes
- Non-Warrantable Condos, Condotels and 2-4 unit properties acceptable
- Rural properties and properties over 10 acres accepted
- Available with 40-Year Fixed-Rate Interest-Only loans
- As little as 12 months seasoning for Bankruptcy, Foreclosure, or Modification
Who This Program Serves
The Expanded Approval program is built for borrowers who are strong overall but have one or two issues that push them outside of conforming eligibility. That might mean a credit score slightly below conventional thresholds, some recent late payments, bank statements with NSFs or overdraft activity, or income that can’t be fully documented through tax returns. Rather than declining outright, we evaluate the full picture — compensating factors like strong reserves, low LTV, and stable cash flow regularly offset what would be automatic denials elsewhere.
This program is particularly useful for brokers who have a borrower that has been declined by a conventional lender but whose financial situation is genuinely sound. The income documentation flexibility means self-employed borrowers, business owners, and asset-rich individuals all have a viable path here.
Income Documentation Options
Full Documentation
traditional income verification for employed or self-employed borrowers with complete tax return history.

Full Doc Self Employed
for business owners with two years of self-employment and complete business and personal returns.

Bank Statement
12 or 24 months of personal or business statements. Variable expense factor applied based on business type. NSFs and overdraft activity reviewed in context rather than used as automatic disqualifiers.

Asset Depletion / Asset Qualifier (Primary Residence Only)
for borrowers with significant liquid assets but limited monthly income documentation. Assets divided over 60 months (qualifier) or 120 months (depletion) to produce qualifying income.

How We Evaluate Complex Files
Our underwriting team reviews exception files with compensating factors rather than applying a binary pass/fail against a guideline grid. Over 40% of the loans we close have had at least one exception. A borrower with strong reserves and a low LTV who has a few late payments from two years ago is a very different risk profile than a guideline violation alone would suggest — and we underwrite accordingly.
NSFs in bank statements are reviewed in context. If the borrower’s overall credit history shows consistent payment behavior and cash flow is stable, NSFs from a difficult period don’t automatically kill the file. We want to understand what happened and whether it’s resolved.
Senior management reviews and signs off on exception approvals. That decision holds through underwriting — the loan is not re-evaluated at a lower level later in the process.
Ready to Submit a Scenario?
Submit your loan scenario or become an approved broker to get started
Frequently Asked Questions
What makes a borrower a good candidate for Expanded Approval vs. another program?
Expanded Approval is the right fit when the borrower has real credit or documentation complexity — not just non-traditional income. A clean self-employed borrower is usually better served by our bank statement or super prime program. Expanded Approval is for borrowers where there’s a credit story to tell alongside the income picture.
Are non-warrantable condos and condotels eligible?
Yes, both property types are permitted under this program.
How flexible are you on NSFs?
NSFs are reviewed in context. We look at frequency, recency, whether bills are being paid on time overall, and whether there’s a logical explanation for the activity. They are not an automatic disqualifier.
What is the maximum loan amount?
Up to $3,000,000 and cash-out up to $1,000,000.
How quickly can a file be reviewed?
Pre-qualification is typically completed within 24 hours of receiving the core documents — no full file required to get a preliminary decision.

August 9, 2024
QM vs Non-QM Loans: Know the Differences & Find the Right Fit
https://youtu.be/3-Px832xF7k?si=C0R3SD6Q8ElJCEg3 …
Read More
August 3, 2023
WEBINAR: Non-QM Strategies - Non-Warrantable Condo Loans
https://youtu.be/fYhFn03DV4c Learn everything you need to know to capitalize on tod…
Read More
September 22, 2026
Innovative Non-QM Niche Programs by LendSure
Every borrower’s scenario is different. That’s why having more financing options mat…
Read More
March 25, 2026
WEBINAR: Non-QM 101: Understanding the Loan Options for Today’s Borrowers
Mortgage loan brokers, get ready to expand your toolbox. This jam-packed webinar will help…
Read More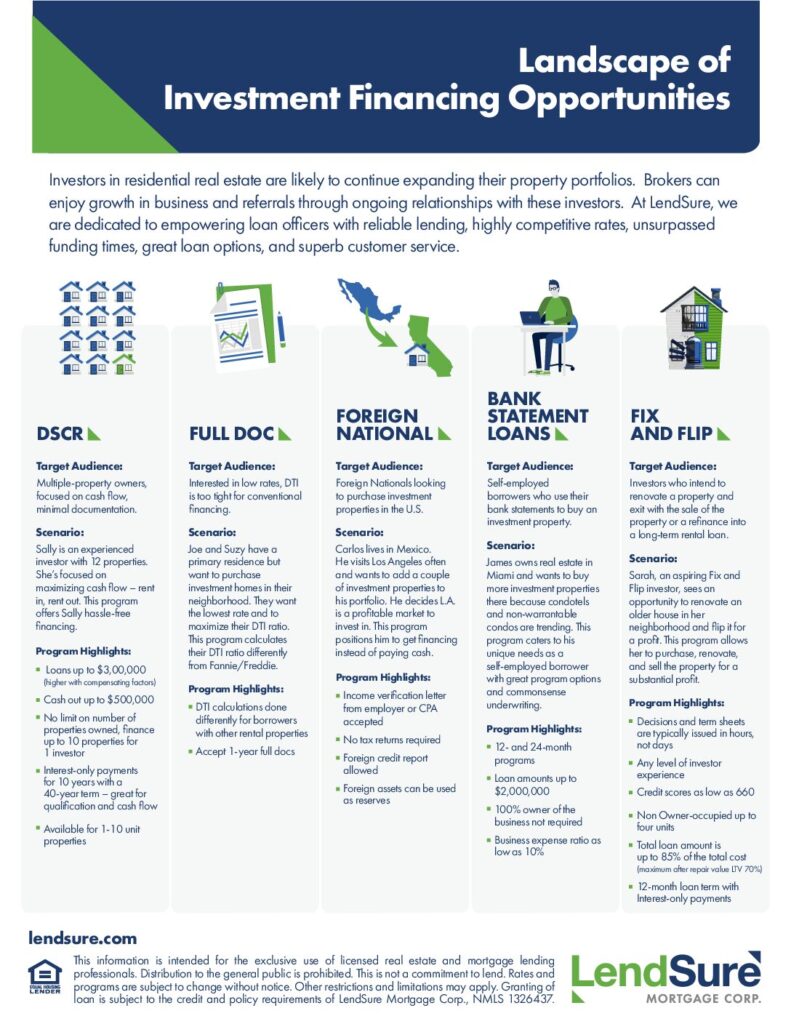
April 5, 2023
WEBINAR: How to Sell Non-QM Part I
https://youtu.be/gE3q8jG54w8 Welcome to our webinar: How to Sell Non-QM Part I! In today�…
Read More
June 23, 2020
LendSure Continues to Expand Non-QM Lending Offerings
FOR IMMEDIATE RELEASE Innovative Loan Programs Expand Mortgage Brokers’ Purchase and Ref…
Read More